BILL Spend & Expense (Divvy)

Screenshots
Details
- Rating
- 555.00 reviews
- Version
- 4.0.17
- Developer
- Bill.com Inc.
Analysis by Norviv
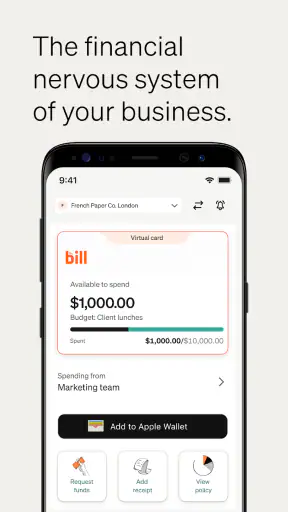
Managing company spending sounds simple until a card payment needs an explanation, a receipt disappears, or an employee is unsure which purchase belongs to which budget. I found BILL Spend & Expense most useful in that space: it brings corporate card activity and expense management into one business-focused app instead of leaving every transaction scattered across email, spreadsheets, and separate card portals. It is a free app from Bill.com Inc., aimed at an Everyone audience, and its business category is clear from the first use.
My overall impression is practical rather than flashy. This is not an app I would install for personal budgeting or casual expense tracking. It makes more sense when several people spend on behalf of an organization and someone needs a cleaner way to review those purchases. The strongest benefit is the connection between spending and accountability. The main challenge is that the app is only one part of a larger company process, so a confusing card setup, an incomplete approval routine, or an account problem outside the app can easily look like an app failure.
Where the real friction appears during everyday use
The first thing I would tell a new user is not to judge the app by how quickly it opens. The important question is whether the account, card activity, and company workflow are already ready to work together. A corporate expense tool depends on information arriving from the organization’s setup. If that foundation is incomplete, the mobile screen may appear limited even when the installation itself went correctly.
Users commonly get stuck when they expect a newly made purchase to behave like a manually entered personal expense. A business transaction may need time to appear, may require a receipt or note, or may wait for an internal review step. That creates a different rhythm from a simple notes app. I found it helpful to treat the app as a place for organizing and responding to business spending, not as an independent accounting system that can repair every missing detail by itself.
Another point of friction is role confusion. An employee, manager, and finance administrator can reasonably expect different things from the same product. One person may mainly need to document a purchase, another may need to inspect spending, and another may oversee the company’s broader process. If someone signs in expecting controls that belong to a different role, the experience can feel incomplete. Before troubleshooting, I would confirm whether the account is being used as a cardholder, reviewer, or administrator.
The app’s store summary focuses on corporate cards and expense management, and that is the right way to understand it. It is not simply a receipt camera with a business label. The value comes from connecting an expense to a company’s spending process. That also means the app is less satisfying for a freelancer who only wants a lightweight list of receipts, especially if there is no need for corporate card oversight.
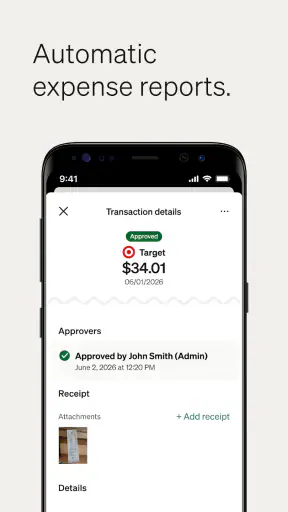
In a realistic workday, imagine an employee buying supplies for a client meeting. The useful workflow is not merely taking a picture of the receipt. The employee needs to recognize the transaction, add enough context for another person to understand it, and complete whatever review step the company expects. If the purchase later looks unfamiliar, the record should help answer who made it, why it happened, and whether it belongs to the business. That context is where this app has more practical value than a generic note-taking tool.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What to check before assuming something is broken
When a transaction seems absent, I would first check the obvious but often overlooked details: whether the correct account is open, whether the relevant card was actually used, and whether the purchase has finished processing. I would also look for a date or merchant detail that makes the transaction easy to overlook. Searching by memory alone is unreliable when several purchases happen close together.
Receipts create a separate kind of confusion. A receipt image can prove what was bought, but it may not explain why the purchase was necessary or which project it serves. I recommend adding a short, specific note while the reason is still fresh. “Client meeting supplies” is more useful to a reviewer than a vague label such as “work.” This is a small habit, but it reduces back-and-forth and makes the record more durable.
The best troubleshooting step is to separate a missing transaction from an incomplete expense record. If the charge itself is visible but the documentation is not finished, the problem is usually workflow completion rather than data arrival. That distinction prevents users from repeatedly reinstalling the app or entering duplicate expenses.
Setup checks that save time later
I would begin by installing the current app version, which is 4.0.17, on a device running at least iOS or Android version 12. That compatibility detail matters before anyone spends time investigating login or display behavior. The app has been available since August 10, 2017, so it is not a new experiment, but an older installation can still create avoidable trouble if the operating system is below the required level.
After installation, I would make sure the sign-in details match the business account rather than a personal account used for another service. This sounds basic, yet it is one of the easiest ways to end up in the wrong environment. If the app opens but shows no useful company activity, I would verify the account identity before changing settings or assuming that the card connection failed.
Next, I would clarify the company’s expected routine. Does every purchase need a receipt? Is a note required? Who reviews the expense? What should an employee do when the merchant name looks unfamiliar? The app cannot make those decisions for a business. Establishing them before the first real purchase gives the mobile workflow a clear purpose and helps users recognize whether they are waiting for a company action rather than an app action.
A useful setup test is a small, ordinary business purchase that everyone can identify. Once it appears, follow it through the same steps an employee would use for a normal expense. Check whether the person can find the transaction, attach the relevant information, and understand what happens next. This is more informative than simply confirming that the app launches, because it tests the complete path from spending to review.
I would also avoid building a process around screenshots or memory. A screenshot may show a charge, but it is not a substitute for a properly documented record. If the business needs a receipt, explanation, or approval, users should complete that work in the intended expense flow. Keeping evidence in the right place makes later review easier and reduces the risk of two separate records describing the same purchase.
How I would prepare a team for fewer mistakes
For a small team, a short written rule is enough: document purchases promptly, use a clear reason, and ask the reviewer when a transaction does not look right. For a larger team, I would add examples of acceptable descriptions and explain which expenses need extra context. This is not glamorous setup work, but it has a bigger effect on day-to-day success than teaching people where every button is located.
I would also tell cardholders not to wait until the end of a busy week to reconstruct expenses. Delayed entry increases the chance of confusing two similar merchants or forgetting the purpose of a purchase. A quick update after the transaction is usually easier than a long cleanup session later. The app is best used as part of the spending habit, not as a monthly memory exercise.
Another practical tip is to keep personal and business purchases mentally separate even when the same person handles both. A business card app cannot make a mixed personal routine clear by itself. If the wrong card is used, the correct response is to follow the organization’s procedure rather than trying to disguise the transaction with an unclear note.
Recovering a workflow when something goes wrong
When an expense is incomplete, I would recover it in stages. First, identify whether the purchase exists as a transaction. Second, gather the missing context: receipt, business purpose, project detail, or explanation. Third, complete the action that the company expects. Keeping those stages separate makes it easier to see whether the issue is visibility, documentation, or review.
If a user sees a duplicate-looking entry, I would not immediately delete or recreate anything. Similar merchant names and nearby purchase dates can make legitimate charges appear repeated. Compare the amount, date, and purpose, then follow the organization’s correction process. Duplicate submissions are especially unhelpful because they create more work for the person reviewing expenses.
If the app appears stuck, I would start with safe checks: confirm the network connection, close and reopen the app, and make sure the device meets the stated minimum operating-system requirement. I would then sign out and back in only if the user is certain the account credentials are available. Reinstalling should be a later step, not the first reaction, because it does not correct a company-side configuration or a transaction that has not finished processing.
For a receipt that will not cooperate, I would preserve the original document and try again under better lighting or with the paper positioned clearly. If the image still cannot be used, I would follow the business’s alternate documentation process rather than creating a fictional replacement. The important principle is accuracy: a less polished but truthful explanation is better than a neat record that hides what happened.
One non-obvious advantage of a staged recovery approach is that it tells you what kind of help to request. If the transaction is missing entirely, the card or account workflow deserves attention. If the transaction is present but incomplete, the employee can usually finish the documentation. If everything is documented but the item remains pending, the reviewer or administrator may be the right person to contact. This avoids sending every problem to the same support channel.
When repeating an action makes the situation worse
Expense systems punish duplication more than ordinary note apps do. Repeatedly tapping submit, entering the same purchase again, or attaching several versions of the same receipt can make a simple delay look like a bookkeeping error. I prefer to wait briefly after a clear action, refresh only once, and inspect the resulting record before trying again.
I would also keep a simple private note of the merchant, purchase date, and reason while resolving a problem. That note is not a replacement for the official record; it is a safety net while the workflow is being repaired. Once the correct entry is visible, the temporary note can be discarded. This is particularly useful when a team member is working away from the office and cannot immediately ask a finance colleague to confirm the next step.
When the app is not the cause
Corporate spending depends on more than the mobile interface. A card may be restricted, an account may have the wrong role, a transaction may still be processing, or the company may not have completed its internal configuration. In those cases, changing phone settings will not solve the underlying issue. The app may simply be displaying the state it has been given.
This is why I would ask a few practical questions before blaming the software. Can another authorized person see the same transaction? Does the problem affect one purchase or every purchase? Is the issue limited to one employee, one card, or one device? These comparisons help isolate the source without inventing a complicated diagnosis.
There is also a human cause: unclear company rules. If employees do not know whether a receipt, explanation, or approval is expected, the app can feel inconsistent because each person uses it differently. A finance manager may interpret an unfinished record as negligence, while the cardholder may believe the charge alone was enough. The fix is a shared process, not necessarily a new app.
Compared with a spreadsheet, BILL Spend & Expense is more closely tied to corporate card activity and can reduce manual copying when the company’s workflow is properly established. Compared with a personal budgeting app, it is more suitable for organizational review and employee spending. Compared with a basic receipt scanner, it asks users to think about the business context of a purchase, which is useful for accountability but may feel like extra effort for someone who only wants to archive receipts.
That comparison also shows when I would choose something else. A solo user with occasional invoices may prefer a simpler accounting or receipt tool. A company that needs a highly specialized travel, mileage, or accounting workflow should compare its requirements carefully before committing. This app makes the most sense when corporate cards and expense oversight are central, not when those needs are incidental.
Who should use it and who should skip it
I would recommend it to teams that want employees to handle business purchases in a more organized way and want reviewers to see useful context instead of unexplained charges. It is also a reasonable fit for a growing business that has outgrown informal receipt folders and scattered spreadsheets. The free price makes trying it less of a financial commitment, while the business focus keeps the workflow aimed at company spending rather than household budgeting.
I would be more cautious for someone who works alone and rarely uses a corporate card. That person may find the structure heavier than necessary. I would also hesitate to recommend it to a team unwilling to define who reviews expenses or what information each purchase needs. No expense app can compensate for a process where nobody owns the follow-up.
The audience rating is Everyone, which makes the app broadly approachable from an age-rating perspective. That does not mean every business will find it equally simple. Ease of use depends heavily on the organization’s account setup and the clarity of its internal rules. In my experience, the app rewards disciplined routines more than casual experimentation.
Its public reception is encouraging: it holds a 4.5 average from around 4.3 thousand ratings, with over 500 reviews and more than 100 thousand installs. Those figures suggest a meaningful user base and a generally positive response, but they should not replace a check against your own company’s needs. A well-rated business tool can still be the wrong choice if its workflow does not match how your team buys, documents, and reviews expenses.
My practical verdict after using the workflow
BILL Spend & Expense is most convincing when treated as a shared business process on a phone, not as a magic fix for messy finances. I like the focus on corporate cards and expense management, and I appreciate that its usefulness grows when employees add context promptly. The app can make routine spending easier to understand, especially when a reviewer needs more than a merchant name and an amount.
My reservations are mostly about dependency and friction. A user can be perfectly capable of using the app and still be blocked by account roles, card status, processing delays, or unclear company expectations. The setup therefore deserves as much attention as the taps inside the app. Teams should test a complete purchase workflow before rolling it out broadly and should teach people how to distinguish a missing transaction from an unfinished record.
For a business already using the BILL ecosystem and looking for a mobile way to keep corporate spending organized, I think it is worth trying. For personal budgeting, occasional receipt storage, or a highly specialized accounting routine, I would look elsewhere. My final recommendation is straightforward: choose it when shared expense accountability is the problem you need to solve, and prepare the surrounding company process before expecting the app to do all the work.
Frequently Asked Questions
01What is BILL Spend & Expense (Divvy), and who is it designed for?
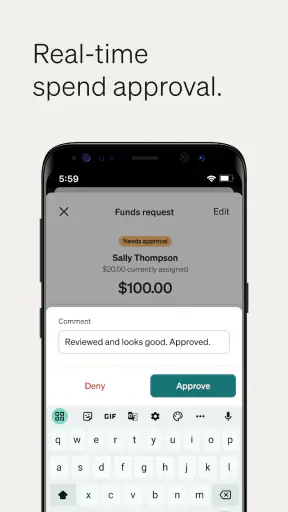
BILL Spend & Expense, formerly known as Divvy, is a business spending and expense-management platform designed for companies, finance teams, and employees. It combines corporate cards, budgets, expense tracking, receipt collection, approvals, and reporting in one system. It is primarily intended for organizations rather than personal budgeting, and access to features usually depends on an employer’s account and administrator settings.
02Can employees use the app to submit receipts and track business expenses?
Yes. Employees can generally use the mobile app to record business purchases, upload or photograph receipts, review transactions, and provide details required by their company. Depending on the organization’s configuration, the app may also support expense categorization, comments, mileage or reimbursement workflows, and reminders for missing information. Available tools can vary according to the company’s subscription, policies, and user permissions.
03Does BILL Spend & Expense provide corporate cards and spending limits?
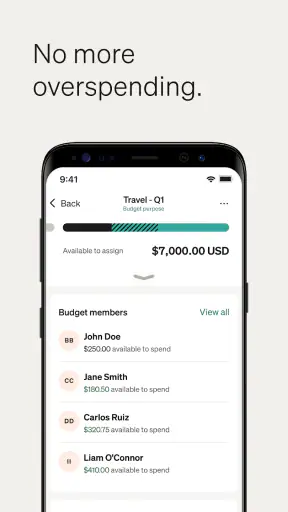
The platform can provide businesses with corporate card and spending-management capabilities, including budget controls, assigned spending limits, and visibility into transactions. Administrators may be able to create budgets, issue or manage cards, establish approval rules, and monitor spending as it occurs. However, eligibility, card availability, funding arrangements, and specific controls depend on BILL’s terms and the organization’s account setup.
04Is my financial and company information secure in the app?
BILL Spend & Expense handles sensitive business, payment, and employee information, so security is an important consideration. The service uses account authentication and organizational permissions to help control access, while companies can apply internal policies to protect data. Users should still use strong, unique passwords, keep devices updated, avoid sharing login details, and report suspicious activity. Review BILL’s current privacy and security documentation before use.
05Is BILL Spend & Expense free to download and use?
The application may be available to download without an upfront charge, but that does not necessarily mean the full service is free. BILL Spend & Expense is a business platform whose pricing, card programs, processing terms, and available features are generally determined by the company’s agreement with BILL. Employees may receive access through their employer, while administrators should review current pricing, eligibility, and contract conditions before signing up.


